
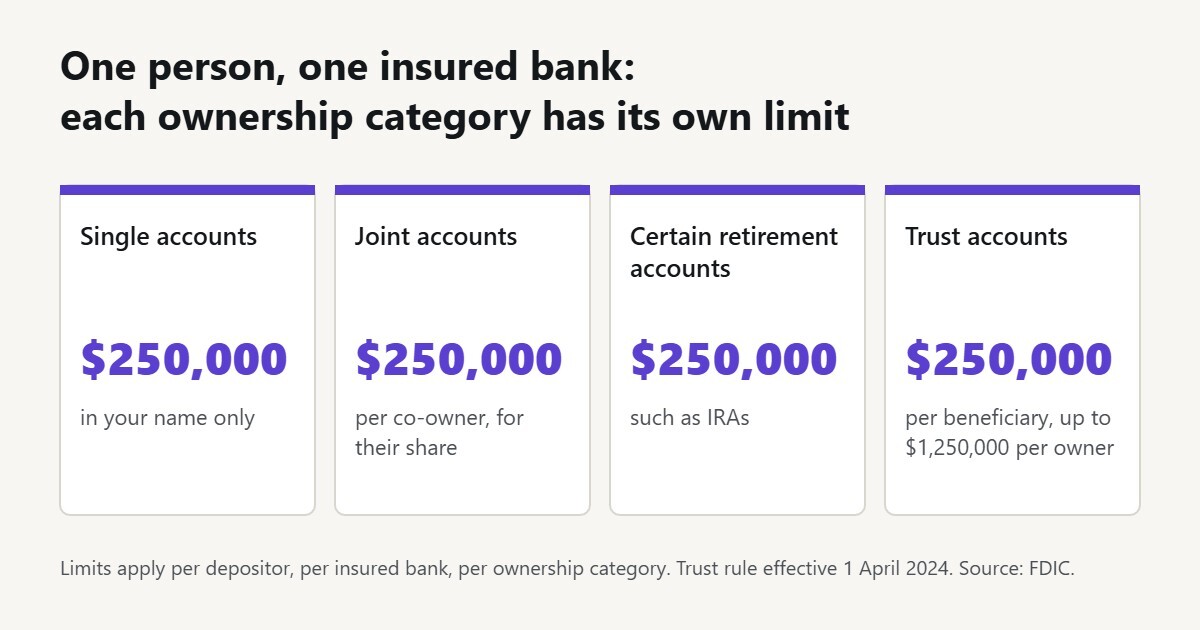
Deposit insurance is not per account, and not per bank in the way most people picture. It is per depositor, per insured bank, per ownership category — and the third term is where the money goes missing.
Enter what you hold. Nothing is sent anywhere; the arithmetic runs in your browser.Money that is not in a bank at all
Two things sit outside the system entirely. Both were expensive lessons for somebody.
—
Worked example: a couple with a joint account
Two people, one bank. Each co-owner of a joint account is insured up to $250,000 for their share of all joint accounts at that bank, and the FDIC assumes equal shares unless the bank’s records say otherwise. Accounts in one person’s sole name are a separate category with their own $250,000.
| Account | Held | Insured | Not insured |
|---|---|---|---|
| Joint account (two co-owners) | $600,000 | $500,000 | $100,000 |
| Partner A, sole name | $200,000 | $200,000 | $0 |
| Partner B, sole name | $300,000 | $250,000 | $50,000 |
| Total at this bank | $1,100,000 | $950,000 | $150,000 |
Moving $150,000 to a second insured bank would bring the uninsured amount to zero. Source: FDIC, “Joint Accounts,” Deposit Insurance Coverage Guide (2024).
When the cover can fall short
| Situation | What the rule does | What to check |
|---|---|---|
| Two accounts in the same ownership category at the same bank | They are added together and share one $250,000 limit. | Use another category or another insured bank. |
| Your bank merges with another bank where you also hold money | Deposits from the bank that was taken over stay separately insured for at least six months after the merger. | Recheck your totals before the six months end. |
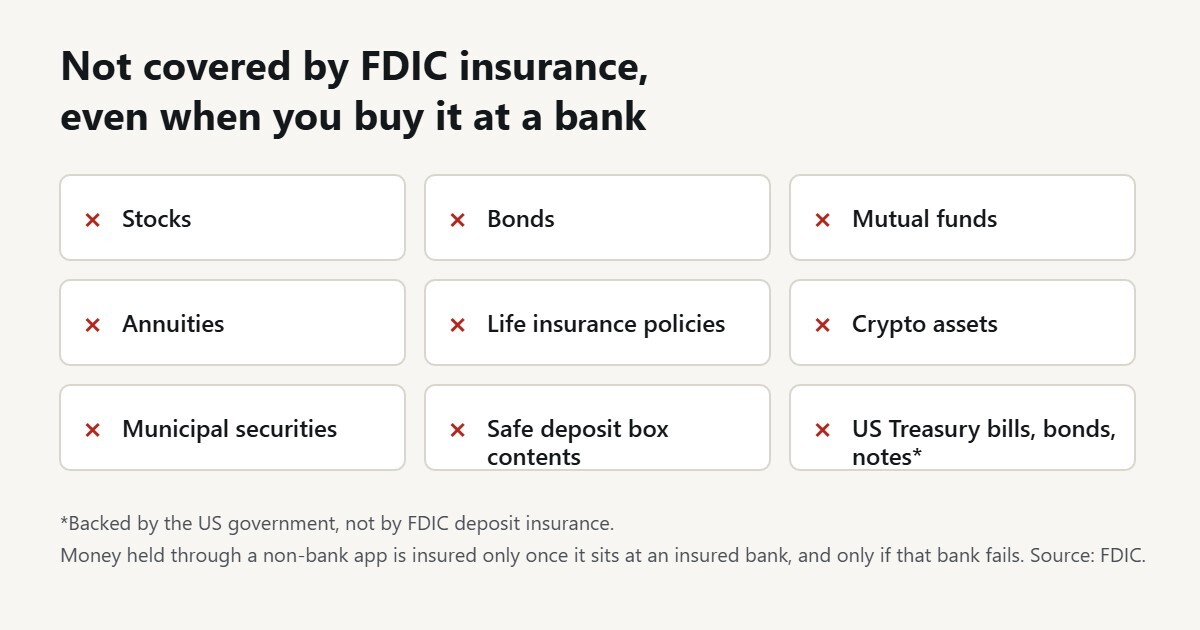
| Money held through an app or fintech that is not itself a bank | FDIC cover applies only once the money sits at an insured bank, and only if that bank fails. It does not cover the app company failing. | Find out which bank holds the money, and in whose name. |
| Investments bought at your bank | Stocks, bonds, funds, annuities and crypto are not deposits, so they are not insured. | See the chart below. |
Sources: FDIC, Your Insured Deposits; FDIC, Merger of IDIs (the six-month rule, 12 C.F.R. § 330.4).
Related on ROR Labs: Deposit insurance: what happens above $250,000 · Bank branch closures and access to cash
What this is. Arithmetic on the published FDIC rules, nothing more. It applies to deposits at US insured banks. It is not advice about your money, and it cannot see the things that actually decide a case — whose name is on what, how a trust is written, whether the institution is insured at all.
What the record shows. Uninsured depositors lost money in 63 per cent of US bank failures between 1992 and 2007, and in about 6 per cent from 2008 onwards. That second number is a pattern of behaviour, not a promise. The mechanism used to rescue uninsured depositors at Silicon Valley Bank required a supermajority of two federal boards and the Treasury Secretary, and nobody can invoke it on your behalf in advance.
Rules: FDIC standard maximum deposit insurance amount, $250,000 per depositor, per insured bank, per ownership category; trust accounts insured at $250,000 per beneficiary to a maximum of $1,250,000 per owner per bank, under the rule effective 1 April 2024. The FDIC publishes its own estimator at edie.fdic.gov. The figures on failures and rescues are from Deposit Insurance: What Happens Above $250,000.
Before you rely on this
This is a reference, not a verdict. It works from published rules and published research, applied to the handful of things you typed in. Real situations turn on details it never sees — whose name is on what, how a document is worded, which rules apply where you live, the specific facts of your case, and factors nobody has measured yet. A different answer from a professional who can see all of it is the one to trust.
Averages are not predictions. Where a figure here comes from a study, it describes what happened to a group of people on average. It does not say what will happen to you. An average is the right tool for deciding what to change and the wrong tool for deciding what is going to happen.
Nothing here is advice. Not financial, legal, medical, insurance or safety advice, and using this page creates no professional relationship of any kind. The sources are linked so you can check them yourself. For a decision that matters, ask someone who is accountable for the answer.